Let’s hit the road and dive into the dynamic world of auto insurance in Massachusetts. If you’re pondering over “how much is auto insurance in Massachusetts,” buckle up because we’re about to explore the intricacies of auto coverage in the Bay State. From understanding the essentials of what’s covered to deciphering those tricky state regulations, this guide will map out everything you need to know.
In Massachusetts, auto insurance isn’t just about numbers; it’s a careful balance of compliance and protection. Whether you’re a new driver or a seasoned pro, knowing the right coverage at the right price can feel like navigating a high-speed chase. But fear not! With this comprehensive overview, we’ll steer you through the maze of costs, coverage options, and smart strategies to get the best deal on your auto insurance.
Overview of Auto Insurance in Massachusetts
Did you know that Massachusetts has one of the most unique auto insurance landscapes in the country? It’s true! If you’re planning to drive in the Bay State, there are a few key things you need to know.
Massachusetts requires all drivers to have a minimum level of insurance coverage, which includes Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property. BUT, that’s just scratching the surface. Most drivers opt for additional coverage to protect themselves further.
Basic Components of Auto Insurance Policies in Massachusetts
Here is the deal: Massachusetts auto insurance policies are broken down into a few essential components. At a minimum, you need coverage for Bodily Injury to Others, which takes care of injuries you cause to other people. Then there’s the Personal Injury Protection (PIP), which covers medical expenses for you and your passengers, regardless of who was at fault.
The state also mandates Bodily Injury Caused by an Uninsured Auto coverage. Why? Because accidents with uninsured drivers happen more often than you think. Finally, you must have Damage to Someone Else’s Property coverage, which pays for repairs if you damage someone else’s property.
State-Specific Insurance Requirements and Regulations
Understanding state regulations is crucial. Massachusetts enforces a no-fault insurance system. This means your own insurance covers your injuries and damages first, regardless of who was at fault. Here’s a quick overview of the minimum requirements:
- Bodily Injury to Others: $20,000 per person / $40,000 per accident
- Personal Injury Protection (PIP): $8,000 per person
- Bodily Injury Caused by an Uninsured Auto: $20,000 per person / $40,000 per accident
- Property Damage: $5,000 per accident
Pro Tip: Always consider buying more than the state minimums. It’s a small price to pay for peace of mind.
Types of Coverage Most Commonly Purchased by Massachusetts Drivers
If you think Massachusetts drivers only stick to the basics, think again. Many drivers add Collision Coverage, which pays for damage to your car after hitting another vehicle or object. Comprehensive Coverage is also popular—it covers non-collision related incidents like theft or natural disasters.
Finally, let’s not forget about Underinsured Motorist Coverage. It steps in when the other driver doesn’t have enough insurance to cover your costs. Consider these options to avoid unexpected out-of-pocket expenses.
Factors Influencing Auto Insurance Costs in Massachusetts

Ever wondered why your auto insurance bill is sky-high? You’re not alone. In Massachusetts, several key factors can dramatically change what you pay.
Understanding these elements can save you big bucks on your premiums. Let’s dive into the details.
Personal Characteristics
Insurance companies love to analyze personal data. Your age and driving history are often the first things they look at. Why? Because younger drivers and those with a history of accidents or violations tend to file more claims.
| Factor | Impact | Example | Explanation |
|---|---|---|---|
| Age | Higher rates for young drivers | A 17-year-old vs a 30-year-old | Young drivers are statistically more risky, leading to higher premiums. |
| Driving History | Significant surcharges for violations | A clean record vs multiple speeding tickets | Violations indicate risky behavior, thus increasing costs. |
Pro Tip: Keep a clean driving record to qualify for discounts!
Location and Vehicle Type
Where you live and what you drive are also crucial. Urban areas with higher traffic and crime rates often mean higher premiums. The type of vehicle you drive matters too—luxury cars cost more to insure.
| Factor | Impact | Example | Explanation |
|---|---|---|---|
| Location | Higher costs in urban areas | Boston vs a rural town | More traffic and thefts increase the insurance risk in cities. |
| Vehicle Type | Premiums vary by model | SUV vs sports car | Sports cars are pricier to repair, impacting insurance rates. |
Here is the deal: If you’re looking to lower your insurance rates, focus on what you can control. Drive safely, choose your location and vehicle wisely, and watch those costs drop!
Average Cost of Auto Insurance in Massachusetts
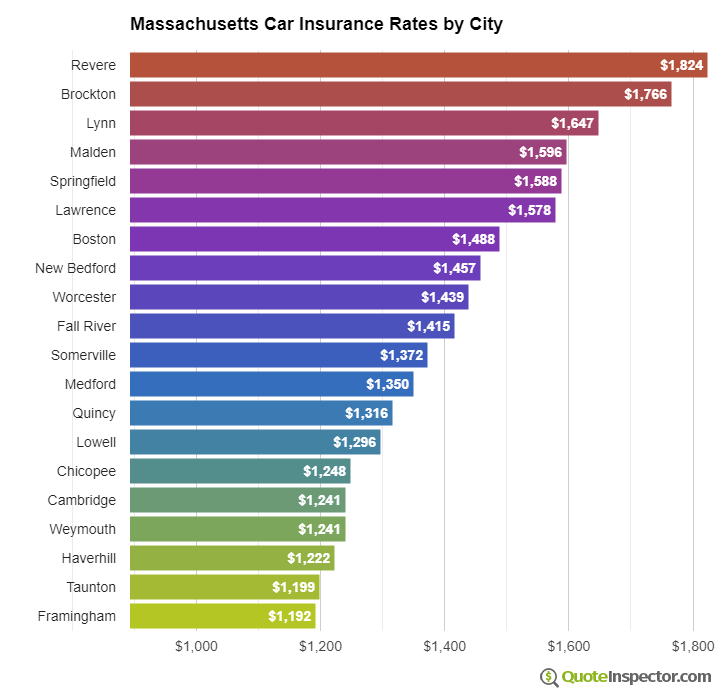
Did you know that Massachusetts has some of the highest auto insurance rates in the U.S.? It’s true. But how does it stack up against the national average?
The average cost of auto insurance in Massachusetts often surprises drivers. Many expect it to be lower given the state’s size, yet factors like traffic density and weather conditions drive rates up. Here’s a breakdown of how Massachusetts compares with the national average over recent years:
| Year | Massachusetts Average | National Average | Difference |
|---|---|---|---|
| 2021 | $1,460 | $1,321 | $139 |
| 2022 | $1,510 | $1,348 | $162 |
| 2023 | $1,535 | $1,380 | $155 |
As you can see, Massachusetts drivers consistently pay more than the national average. BUT there’s more to it than just the state you’re in.
Impact of Coverage Levels on Auto Insurance Cost
Not all insurance plans are created equal. Your choice between liability coverage and full coverage can drastically alter your premium. Here’s how:
- Basic liability coverage may cost around $900 annually.
- Full coverage, which includes collision and comprehensive, typically exceeds $1,500.
Here is the deal: Opting for full coverage can nearly double your cost. BUT, it also provides significantly more protection in accidents or natural disasters.
Pro Tip: Consider raising your deductible to lower your premium if you opt for full coverage.
So, while Massachusetts has higher averages, your personal choices and driving record can make a big difference in your rates.
Tips for Saving on Auto Insurance in Massachusetts
Did you know that auto insurance costs in Massachusetts can vary by hundreds of dollars depending on what you do? Crazy, right? But you don’t have to break the bank to get the coverage you need.
Whether you’re a new driver or someone looking to cut down on costs, there are a ton of ways to save. Let’s dig into some actionable strategies you can use to lower your premiums today.
Smart Ways to Lower Your Premiums
Your auto insurance premium doesn’t have to be set in stone. With a few adjustments, you can potentially save a significant amount of money. Here’s how:
- Bundle Your Policies: Combine your auto insurance with other policies like home or renters’ insurance for a discount.
- Choose a Higher Deductible: Opt for a higher deductible to lower your monthly premium. Just make sure you can afford the deductible in case of a claim.
- Maintain a Clean Driving Record: Avoid accidents and traffic violations to qualify for safe driver discounts.
- Shop Around: Don’t settle for the first quote you get. Compare rates from different insurers to find the best deal.
- Take Advantage of Discounts: Look for discounts like those for good students, low mileage, or having safety features in your car.
- Review Your Coverage: Consider dropping unnecessary coverage, especially if you have an older vehicle that’s not worth much.
Pro Tip: “Many insurers offer discounts for simply paying your premium annually instead of monthly.”
Comparison of Insurance Providers in Massachusetts
Did you know that the average driver in Massachusetts could be saving hundreds of dollars annually just by switching insurance providers? It’s true! But with so many options on the table, how do you know which one to choose?
Here is the deal: not all insurance providers are created equal. Some offer competitive rates but lack in customer service, while others might have stellar reviews but come with a hefty price tag. Let’s break it down and see what major insurance players in Massachusetts have to offer.
Key Insurance Providers and Their Offerings
When comparing insurance providers, we look at three main factors: coverage options, customer satisfaction, and average premium costs. This comparison will give you a clearer picture of what to expect from each provider.
| Provider | Coverage Options | Customer Ratings | Average Premium |
|---|---|---|---|
| Geico | Comprehensive, Collision, Liability, Uninsured Motorist | 4.5/5 | $1,200 |
| Progressive | Comprehensive, Collision, Rental, Roadside Assistance | 4.3/5 | $1,250 |
| State Farm | Comprehensive, Collision, Rideshare, Emergency Road Service | 4.2/5 | $1,300 |
| Liberty Mutual | Comprehensive, Collision, Gap Coverage, New Car Replacement | 4.0/5 | $1,400 |
Pro Tip: If you’re looking to save money, consider bundling your auto insurance with home insurance from the same provider. Many companies offer significant discounts when you do this.
Legal Considerations and Resources for Massachusetts Drivers
Did you know that driving without insurance in Massachusetts can lead to some serious penalties? Many drivers are unaware of the legal obligations they face on the road.
Massachusetts law requires you to maintain a minimum level of auto insurance coverage. Without it, you risk facing hefty fines, license suspension, and even jail time. But there’s more to this than just penalties.
Penalties for Driving Without Insurance
Here’s the deal: If you’re caught driving uninsured in Massachusetts, you could be looking at a $500 fine for the first offense. And it doesn’t stop there. Your license can be suspended for 60 days. Repeat offenders face even harsher consequences, including longer suspensions and higher fines.
But wait, there’s more! Getting caught can also lead to an increase in your insurance premiums once you do get coverage. In other words, not only is it illegal, but it’s also costly in the long run.
State Resources and Assistance Programs
Struggling to find affordable insurance? You’re in luck! Massachusetts offers several resources to help you get covered without breaking the bank.
- The Massachusetts Health Connector provides assistance for low-income individuals seeking auto insurance.
- Massachusetts Division of Insurance offers a detailed guide and comparison tools to help you make informed decisions about coverage.
- If you need personalized help, the Insurance Partnership Program might be worth checking out. It provides guidance for finding affordable plans tailored to your needs.
Pro Tip: Always compare quotes from different providers. A little research can save you a ton of money on your premiums!
Closure
As our journey through the road of Massachusetts auto insurance wraps up, it’s clear that understanding your coverage is just as crucial as knowing your car’s horsepower. With the right knowledge and a strategic approach, you can ensure you’re not only following the law but also optimizing your protection without overspending. Remember, in the world of auto insurance, informed drivers are the true champions on the road.
Answers to Common Questions
What are the basic components of auto insurance policies in Massachusetts?
Auto insurance policies in Massachusetts generally include liability coverage, personal injury protection (PIP), uninsured motorist coverage, and optional collision and comprehensive coverage.
What factors influence auto insurance costs in Massachusetts?
Several factors impact costs, such as your age, driving history, location, and vehicle type. For instance, younger drivers typically face higher premiums, while vehicles with high safety ratings may lower costs.
How does the average cost of auto insurance in Massachusetts compare to the national average?
Massachusetts tends to have higher auto insurance premiums compared to the national average, reflecting its unique regulations and urban density.
What are some tips for saving on auto insurance in Massachusetts?
Consider bundling policies, choosing higher deductibles, maintaining a clean driving record, and exploring discounts for safety features.
What are the consequences of driving without insurance in Massachusetts?
Driving without insurance can lead to fines, license suspension, and increased premiums once insurance is obtained.
